This paper investigates the probability of a spectrally negative Lévy process, killed at a position-dependent rate, crossing an upper boundary, providing new insights into first passage times for such processes and related models.
Contribution
It introduces a novel analysis of first passage probabilities for position-dependent killed spectrally negative Lévy processes, linking to time-changed processes and self-similar Markov processes.
Findings
01
Derived explicit formulas for upward passage probabilities.
02
Connected results to first passage times of self-similar Markov processes.
03
Enhanced understanding of killed Lévy processes with state-dependent rates.
Abstract
For a spectrally negative L\'evy process (snLp) X, killed according to a rate that is a function ω of its position, we analyse the exit probability of the one-sided upwards-passage problem. When ω is strictly positive, this problem is related to the determination of the Laplace transform of the first passage time upwards for X that has been time-changed by the inverse of the additive functional ∫0⋅ω(Xu)du. In particular our findings thus shed extra light on related results concerning first passage times upwards (downwards) of spectrally negative positive self-similar Markov processes (continuous state branching processes).
Figures1
Click any figure to enlarge with its caption.
Figure 1
Equations86
Bq(ω)(x,c):=Px[exp{−∫0τc+ω(Xu)du};τc+<eq].
Bq(ω)(x,c):=Px[exp{−∫0τc+ω(Xu)du};τc+<eq].
s≥ζ
s≥ζ
ρs:=inf{t∈[0,∞):∫0tω(Xu)du>s} for s∈[0,∞).
ρs:=inf{t∈[0,∞):∫0tω(Xu)du>s} for s∈[0,∞).
Py[e−γTd+;Td+<ζ]=Bq(γω)(y,d).
Py[e−γTd+;Td+<ζ]=Bq(γω)(y,d).
Px[e−qτc+;τc+<∞]=e−Φ(q)(c−x).
Px[e−qτc+;τc+<∞]=e−Φ(q)(c−x).
∫0∞e−θxW(λ)(x)dx=ψ(θ)−λ1,θ∈(Φ(λ),∞).
∫0∞e−θxW(λ)(x)dx=ψ(θ)−λ1,θ∈(Φ(λ),∞).
e−Φ(λ)xW(λ)(x)=WΦ(λ)(x)↑ψ′(Φ(λ)+)1 as x↑∞,λ∈[0,∞),
e−Φ(λ)xW(λ)(x)=WΦ(λ)(x)↑ψ′(Φ(λ)+)1 as x↑∞,λ∈[0,∞),
No public reviews on file for this paper yet. If you reviewed it on a platform where reviews are public (OpenReview, ICLR, NeurIPS, ICML), you can paste yours below so the community can read it here.
Videos
No videos yet. Explain this paper in a talk, walkthrough, or lecture? Add one.
Full text
First passage upwards for state dependent-killed spectrally negative Lévy processes
Matija Vidmar
Department of Mathematics, University of Ljubljana, Slovenia
For a spectrally negative Lévy process X, killed according to a rate that is a function ω of its position, we complement the recent findings of [9] by analysing (in greater generality) the exit probability of the one-sided upwards-passage problem. When ω is strictly positive, this problem is related to the determination of the Laplace transform of the first passage time upwards for X that has been time-changed by the inverse of the additive functional ∫0⋅ω(Xu)du. In particular our findings thus shed extra light on related results concerning first passage times downwards (upwards) of continuous state branching processes (spectrally negative positive self-similar Markov processes).
Key words and phrases:
Spectrally negative Lévy processes; first passage upwards; killing; time-changes
2010 Mathematics Subject Classification:
Primary: 60G51; Secondary: 60J25, 60G44
Financial support from the Slovenian Research Agency is acknowledged (research core funding No. P1-0222).
1. Introduction
Let X=(Xt)t∈[0,∞) be a spectrally negative Lévy process (snLp) under the probabilities (Px)x∈R. This means that X is a càdlàg, real-valued process with no positive jumps and non-monotone paths, which, under P0, a.s. vanishes at zero and has stationary independent increments; furthermore, for each x∈R, the law of X under Px is that of x+X under P0. We refer to [1, 8, 3, 10] for the general background on (the fulctuation theory of) Lévy processes and to [1, Chapter VII] [8, Chapter 8] [3, Chapter 9] [10, Section 9.46] for snLp in particular. As usual we set P:=P0. For c∈R denote next by τc+:=inf{t∈(0,∞):Xt>c} the first hitting time of the set (c,∞) by the process X. Further, let q∈[0,∞) and let eq be an exponentially with mean q−1 distributed random variable (e0=∞ a.s.) independent of X (under Px for all x∈R). Finally, let ω:R→[0,∞) be Borel measurable and locally bounded. Then, for real x≤c, we will be interested in the quantity111Throughout we will write Q[W] for EQ[W], Q[W;A] for EQ[W\mathbbm1A], Q[W∣A] for EQ[W∣A] (A an event) and Q[W∣G] for EQ[W∣G] (G a sub-σ-field).
[TABLE]
This may be interpreted as the ultimate passage probability of X, killed at eq, over the level c, when started at x, under “ω-killing”, i.e. when X is killed (in addition to being killed at the time eq) according to a rate that depends on the position of X and that is given by the function ω. Of course Bq(ω)(x,c)=B0(ω+q)(x,c), but it will be convenient to keep the independent exponential killing separate.
Assume now that ω is strictly positive everywhere. Our main motivation for the interest in (1.1) comes from its involvement in the solution of the first passage problem upwards for the process that we will denote by Y=(Ys)s∈[0,∞), and that is defined as follows. Setting ζ:=∫0eqω(Xu)du (see [4] for conditions on the finiteness/divergence of this integral in the case q=0, i.e. eq=∞), then
[TABLE]
with
[TABLE]
Notice that ρ is continuous (because ω is strictly positive, and hence ∫0⋅ω(Xu)du strictly increasing) and it is strictly increasing where it is finite (because ω is locally bounded, and hence ∫0⋅ω(Xu)du continuous). Thus the paths of Y up to ζ are the same as the paths of X up to eq – modulo the random time change ρ. Also, if F=(Ft)t∈[0,∞) is any filtration relative to which X is adapted and has independent increments, with eq independent of F∞, then thanks to the strong Markov property of X and the memoryless property of the exponential distribution, the process Y is Markovian with state space (R,BR) and life-time ζ under the probabilities (Py)y∈R and in the filtration G=(Gs)s∈[0,∞):=(Fρs∨σ({{ρu<eq}:u∈[0,s]}))s∈[0,∞), in the precise sense that it is G-adapted and that for any Borel measurable h:R→[0,∞], and any y∈R, t∈[0,∞), a.s.-Py, Py[h(Yt+s)\mathbbm1{t+s<ζ}∣Gt]=PYt[h(Ys);s<ζ]\mathbbm1{t<ζ}. (Of course if in addition one has a P∂ such that Yt=∂ for all t∈[0,∞) a.s.-P∂, then as a consequence Y is also simply Markovian with state space (R∪{∂},σ(BR∪{{∂}})) and infinite life-time.)
By way of example, when ω=exp and ∂=−∞, then, under the probabilities (Plogx)x∈(0,∞), S:=exp(Y) is a spectrally negative positive self-similar Markov process (pssMp) absorbed at the origin, with index of self-similarity 1, associated to X via the Lamperti transform for pssMp [8, Theorem 13.1]. And, for c∈(0,∞), on {τlogc+<eq}, ∫0τlogc+exp(Xu)du is the first time that S hits the set (c,∞), the latter time being =∞ on the complement of {τlogc+<eq}. See Example 6. Similarly, for c∈(0,∞), with ω(x)=∣x∣1 for x∈(−∞,−c] and again ∂=−∞, −Yτ−c+ becomes, under the probabilities (P−x)x∈[0,∞), a continuous state branching process (csbp) B stopped on hitting the set [0,c), where B is the csbp associated to −X under the Lamperti transform for csbp [8, Theorem 12.2].222We are forced to stop at τ−c+ in order to remain in the setting of a locally bounded ω, which is an assumption that remains in force throughout this paper. And, on {τ−c+<eq}, ∫0τ−c+∣Xu∣du is the first time B hits [0,c), the latter time being =∞ on the complement of {τ−c+<eq}. See Example 8.
More generally, denote for d∈R, by Td+:=inf{s∈(0,∞):Ys∈(d,∞)} the first hitting time of the set (d,∞) by the process Y. Then, for γ∈[0,∞), and real y≤d, under Py, the Laplace transform of Td+=∫0τd+ω(Xu)du on {Td+<ζ}={τd+<eq}, at the point γ, is given simply by
[TABLE]
Moreover, knowledge of this expression automatically furnishes also the joint Laplace transform of τd+ and Td+: if further p∈[0,∞), then Py[e−γTd+−pτd+;Td+<ζ]=Bq+p(ω)(y,d).
Literature-wise, fluctuation results for the “ω-killed” snLp X have been the subject of the substantial recent study of [9] to which the reader is referred for a further review of existing and related results as well as extra motivation for considering such processes.
Our contribution is only a small complement to the findings of [9], but still one that seems to deserve recording. To be precise, [9] provides information on the one-sided upwards passage problem when ω is constant on (−∞,0] (see [9, Section 2.4]); we will extend this to a far more general class of functions ω. In this class, the solution to (1.1) will be given in terms of a function Hq(ω) that will be found to solve (uniquely) a natural convolution equation on the real line involving the q-scale function of X (Theorem 2). In contrast to the two-sided exit problem, where the pertinent convolution equation is on the nonnegative half-line [9, Eq. (1.2)], this introduces some extra finiteness issues, making the analysis slightly more delicate. The function Hq(ω) will also be associated with a family of (local) martingales involving the process Y (Proposition 12).
To avoid unnecessary repetition we turn to the results and their proofs presently in Section 3, after briefly introducing some necessary further notation and recalling some known facts in Section 2. Section 4 concludes by illustrating the findings in the context of determining the optimal level at which to sell an asset whose price process is given by the exponential of the process Y from (1.2).
2. Further notation and some preliminaries
We denote by ψ the Laplace exponent of X, ψ(c):=logP[ecX1] for c∈[0,∞); and by Φ its right-continuous inverse, Φ(p):=inf{c∈[0,∞):ψ(c)>p} for p∈[0,∞); ψ is strictly convex and continuous, lim∞ψ=∞ and Φ(0) is the largest zero of ψ. For real x≤c recall the classical identity [8, Eq. (3.15)]
[TABLE]
Further, for λ∈[0,∞), W(λ):R→[0,∞) will be the λ-scale function of X, characterized by being continuous on [0,∞), vanishing on (−∞,0), and having Laplace transform
[TABLE]
In particular we set W(0)=:W. The reader is referred to [7] for further background on scale functions of snLp; we note explicitly only the asymptotic behavior [7, Eq. (33), Lemmas 2.3 and 3.3]
[TABLE]
that we shall use repeatedly in what follows (here 1/0:=∞ when λ=Φ(0)=ψ′(0+)=0, and otherwise ψ′(Φ(λ)+)∈(0,∞); WΦ(λ) is the scale function of an Esscher transformed process – its precise character is unimportant, what matters is only the monotone convergence).
Convolution on the real line will be denoted by a ⋆: for Borel measurable f,g:R→R,
[TABLE]
whenever the Lebesgue integral is well-defined.
Finally, it will be convenient to introduce the following concepts.
Definition 1**.**
For a function f:R→R, we will (i) say that it has a bounded left tail (resp. left tail that is bounded below away from zero) if f is bounded (resp. bounded below away from zero) on (−∞,x0] for some x0∈R; (ii) for further α∈[0,∞), say that it has a left tail that is α-subexponential provided that for some x0∈R, some γ<∞, and then all x∈(−∞,x0], one has ∣f(x)∣≤γeαx; and (iii) say simply that it has a subexponential left tail if, for some α>0, it has a left tail that is α-subexponential.
3. Results and their proofs
Here is now the main result of this note.
Theorem 2**.**
There exists a unique function Hq(ω):R→(0,∞) satisfying (the arbitrary normalization condition) Hq(ω)(0)=1 such that
[TABLE]
The function Hq(ω) enjoys the following properties.
(I)
It is nondecreasing (hence locally bounded), continuous, and it is strictly increasing provided ω>0.
2. (II)
For each c∈R the following holds: ω1(⋅∧c)=ω2(⋅∧c) implies H(ω1)(⋅∧c)=αH(ω2)(⋅∧c) for some α∈(0,∞); this α being 1 if c≥0.333ω1(⋅∧c) means the function (R∋x↦ω1(x∧c)). More generally, throughout this text, given an expression R(x) defined for x∈R we will write R(⋅) for the function (R∋x↦R(x)).
3. (III)
If ω1,ω2:R→[0,∞) are both locally bounded and Borel measurable with ω1≤ω2 (resp. ω1<ω2), then Hq(ω1)≤Hq(ω2) (resp. Hq(ω1)<Hq(ω2)) on (0,∞) and Hq(ω1)≥Hq(ω2) (resp. Hq(ω1)>Hq(ω2)) on (−∞,0) (of course Hq(ω1)(0)=1=Hq(ω2)(0)).
4. (IV)
For real x≤c, Hq(ω)(x)≤Hq(ω)(c)e−Φ(q)(c−x), in particular Hq(ω)(x)≤eΦ(q)x for all x∈(−∞,0], so that Hq(ω) has a left tail that is Φ(q)-subexponential.
Furthermore, if (ωeΦ(q+p)⋅)⋆W(q) is finite-valued for all p∈(0,∞), then for some unique Lq(ω)∈[0,1], Hq(ω) satisfies the convolution equation
[TABLE]
More specifically:
(i)
If moreover ω has a left tail that is bounded and bounded below away from zero, then Hq(ω) satisfies the (homogeneous) convolution equation
[TABLE]
2. (ii)
If even (ωeΦ(q)⋅)⋆W(q) is finite-valued, in particular if ω has a subexponential left tail, then Hq(ω) is the unique locally bounded Borel measurable function H:R→R admitting a left tail that is Φ(q)-subexponential and satisfying the (inhomogeneous) convolution equation
[TABLE]
where
[TABLE]
This function is given as Hq(ω)=↑–limn→∞Hn, where H0:=Lq(ω)eΦ(q)⋅ and recursively Hn+1:=Lq(ω)eΦ(q)⋅+(ωHn)⋆W(q) for n∈N0.
After some remarks and examples we turn to the proof of this theorem on p. 3.
Remark 3*.*
Since Hq(ω)=H0(ω+q), (3.3) may be rewritten as Hq(ω)=((ω+q)Hq(ω))⋆W. For the same reason, when q>0, then automatically Hq(ω)=((ω+q)Hq(ω))⋆W.
Remark 4*.*
Because of (2.3) cases i and ii are seen to be mutually exclusive (but they are not exhaustive). Of course (ωeΦ(q+p)⋅)⋆W(q) is finite-valued for all p∈(0,∞) iff (ωeα⋅eΦ(q)⋅)⋆W(q) is finite-valued for all α∈(0,∞), in which case, for each α∈(0,∞), ωeα⋅ falls under the provisos of ii. For the resulting convolution equation (3.4) we then have suitable uniqueness of the solution as well as an explicit recursion to (at least in principle) produce it. At the same time, by bounded convergence in (3.1)-(1.1), limα↓0Hq(ωeα⋅)=Hq(ω).
Example 5*.*
When ω is constant and equal to some μ∈[0,∞), then (2.1) Hq(ω)=Hq(μ)=eΦ(q+μ)⋅, and this case falls under i or ii, according as μ>0 or μ=0.
Example 6*.*
When ω=γeα⋅, with γ∈[0,∞) and α∈(0,∞), a case that falls under ii, one obtains using (2.2)
[TABLE]
with the series converging to finite values. (As usual the empty product is interpreted as being equal to 1.) Of course when γ>0, then from (3.1), by spatial homogeneity, Hq(γeα⋅)(x)=Hq(eα⋅)(α1logγ)Hq(eα⋅)(x+α1logγ), x∈R. Note that this reproduces (up to trivial transformations) Patie’s scale functions from the fluctuation theory of spectrally negative pssMp [8, Section 13.7]. One also identifies the limit (3.5) as Lq(γeα⋅)=(∑k=0∞∏l=1k(ψ(Φ(q)+lα)−q)γk)−1.
Remark 7*.*
Let γ∈[0,∞) and α∈(0,∞). Suppose ω(x)≤γeαx for all x∈R. Then, again via (2.2), one gets the following a priori bound on the absolute error in ii from computing only finitely many terms of the recursion for Hq(ω): Hq(ω)−Hn≤Lq(ω)∑k=n+1∞∏l=1k(ψ(Φ(q)+αl)−q)γke(Φ(q)+αk)⋅≤∑k=n+1∞∏l=1k(ψ(Φ(q)+αl)−q)γke(Φ(q)+αk)⋅ for all n∈N0. (In particular Hq(ω)≤Lq(ω)∑k=0∞∏l=1k(ψ(Φ(q)+αl)−q)γke(Φ(q)+αk)⋅≤∑k=0∞∏l=1k(ψ(Φ(q)+αl)−q)γke(Φ(q)+αk)⋅.)
Example 8*.*
Let c∈(0,∞), γ∈(0,∞) and ω(x)=∣x∣γ for x∈(−∞,−c]. Using the result for csbp of [5, Theorem 1] we identify Hq(ω) up to a multiplicative constant;
[TABLE]
where θ∈(Φ(q),∞) is arbitrary but fixed. Note that this ω falls neither under i nor under ii, but it does fall under (3.2). In fact, while it is not so obvious, an easy computation shows that (3.2) is verified in this case with Lq(ω)=0.
Example 9*.*
Let n∈N≥2, γ∈[0,∞), c∈(0,∞) and ω(x)=∣x∣nγ for x∈(−∞,−c]. Except possibly when q=Φ(0)=ψ′(0+)=0, we then automatically have, because of the asymptotic properties of W(q), see (2.3), that (ωeΦ(q)⋅)⋆W(q) is finite-valued, and in any event we assume now that this is so. Then note, using (2.2), that, for x∈(−∞,−c], v∈[Φ(q),∞) and for α>0, dαndn∫0∞(x−y)ne(v+α)(x−y)W(q)(y)dy=ψ(v+α)−qe(v+α)x, which implies ∫0∞∣x−y∣ne(v+α)(x−y)W(q)(y)dy=∫v+α∞dv1∫v1∞dv2⋯∫vn−1∞dvnψ(vn)−qevnx=∫v+α∞dvnψ(vn)−qexvn∫v+αvndvn−1⋯∫v+αv2dv1=∫v+α∞dyψ(y)−qexy(n−1)!(y−v−α)n−1. Hence, letting α↓0, by monotone convergence, ((ωev⋅)⋆W(q))(x)=γ∫0∞∣x−y∣nev(x−y)W(q)(y)dy=γ∫v∞dyψ(y)−qexy(n−1)!(y−v)n−1=γ∫0∞dyψ(v+y)−qex(v+y)(n−1)!yn−1. Thus the recursion of ii allows us to identify Hq(ω), up to a proportionality constant, as an infinite series of iterated integrals;
Let q=0. If ω∣(−∞,0]=0, then Lq(ω)=1 and (3.4) recovers [9, Eq. (2.23) with ϕ=0]. If ω∣(−∞,0]=ϕ∈(0,∞), then Hq(ω)∣(−∞,0]=eΦ(ϕ)⋅ and (3.3) is seen (via W(ϕ)=W+ϕW(ϕ)⋆W, that may be checked by taking Laplace transforms using (2.2); and via ϕeΦ(ϕ)⋅⋆W=eΦ(ϕ)⋅, which follows directly from (2.2)) to be a slight rewriting of [9, Eq. (2.23) with ϕ>0].
2. (b)
In [9, Eq. (2.25)], for real x≤c, the “ω-resolvent” identity ∫0∞Px[exp(−∫0tω(Xu)du);t<τc+,Xt∈dy]dt is formally asserted only for the case when ω∣(−∞,0] is constant, but it prevails of course in full generality (with our H0(ω) replacing the H(ω) there): the proof consists only in using the resolvent identity for the two-sided exit problem [9, Eq. (2.15)] and the fact that H0(ω)(c)H0(ω)(x)=B0(ω)(x,c)=limb→−∞Px[exp{−∫0τc+ω(Xu)du};τc+<τb−]. For this reason we omit reproducing the expression here.
3. (c)
The approach of [9] to handle the case when ω is constant on (−∞,0] is by taking limits in the two-sided exit problem (as indicated in the previous item). We will follow an alternate, more direct route (also inspired by [9]), which will allow us to prove the result in greater generality.
Let x≤y≤c be real numbers. Since X has no positive jumps, then Px-a.s. Xτy+=y on {τy+<∞}, and it follows by the strong Markov property of X applied at the time τy+ and the memoryless property of the exponential distribution, that one has the multiplicative structure
[TABLE]
Furthermore, it is clear that Bq(ω)(x,c)>0 for all real x≤c. As a consequence we may unambiguously define (with a preemptive choice of notation) Hq(ω)(x):=Bq(ω)(0,c)Bq(ω)(x,c) for real x≤c, c≥0. In short, then, Hq(ω):R→(0,∞), Hq(ω)(0)=1, and (3.1) holds. It is clear that Hq(ω) is unique in having the preceding properties.
Statements I-II-III, apart from the continuity of Hq(ω), follow immediately from (3.1)-(1.1) and simple comparison arguments. To prove continuity of Hq(ω) note that for real c, τd+↓τc+ as d↓c, and that further for x∈(−∞,c), by quasi-left-continuity and regularity of [math] for (0,∞), Px-a.s. also τd+↑τc+ (on {limd↑cτd+<∞} and hence everywhere) as d↑c. Then use bounded convergence in (3.1)-(1.1), exploiting the facts that ω is locally bounded and that the law of the overall supremum X∞ has no finite atoms, which implies that a.s.-Px on {τc+=∞} also τd+=∞ for all d<c that are sufficiently close to c. (That the law of X∞ has no finite atoms follows for instance from (2.1) and the continuity of Φ.) For IV, notice that by (2.1), Hq(ω)(x)≤Hq(ω)(c)Px(τc+<eq)=Hq(ω)(c)Px[e−qτc+;τc+<∞]=Hq(ω)(c)e−Φ(q)(c−x) for real x≤c.
We now prove i. Since the homogeneous convolution equation (3.3) may be checked “locally”, separately on each (−∞,c] for c∈R, we may assume (replacing ω by ω(⋅∧c) if necessary) that ω is bounded by a λ∈(0,∞). Also, there is an x0∈R such that ω is bounded below away from zero on (−∞,x0] by some a>0. Let again x≤c be real numbers. Then, using the resolvent [7, Theorem 2.7(ii)]
[TABLE]
as well as the classical identity (2.1) Px[e−λτc+;τc+<eq]=e−Φ(λ+q)(c−x), it follows via the marked Poisson process technique of [9] – letting (Ti)i∈N be the arrival times of a homogeneous Poisson process of intensity λ, marked by an independent sequence (Mi)i∈N of i.i.-uniformly on [0,λ]-d. random variables – that
[TABLE]
[TABLE]
[TABLE]
Next, plugging (3.1) into (3.7), multiplying both sides by Hq(ω)(c) and letting c↑∞, we obtain by monotone convergence using (2.3) that
[TABLE]
with hλ:=limc→∞Hq(ω)(c)e−Φ(λ+q)c; a priori this limit must exist in [0,∞). Now convolute both sides of the preceding display by λW(q), exploiting the relations eΦ(λ+q)⋅=λeΦ(λ+q)⋅⋆W(q) (which is a direct consequence of (2.2)) and W(λ+q)=W(q)+λW(λ+q)⋆W(q) (which may be checked by taking Laplace transforms and again using (2.2)) that together imply (ψ′(Φ(λ+q))eΦ(λ+q)⋅−W(λ+q))⋆λW(q)=(ψ′(Φ(λ+q))eΦ(λ+q)⋅−W(λ+q))+W(q), to obtain
[TABLE]
Then the estimate Hq(ω)(x0)Hq(ω)(x)≤e−Φ(q+a)(x0−x) for x∈(−∞,x0] implies (via (2.2) and the local boundedness of Hq(ω) and W(q)) that Hq(ω)⋆W(q) is finite-valued and upon subtracting finite quantities we obtain (3.3). This concludes the proof of i.
Suppose now (ωeΦ(q+p)⋅)⋆W(q) is finite-valued for all p∈(0,∞). From i, for each p∈(0,∞) and n∈N, one has, for all x∈R,
[TABLE]
[TABLE]
We now first pass to the limit n→∞ as follows. In (3.1)-(1.1) monotone (for the integral against the Lebesgue measure) and bounded (for the expectation) convergence yield Hq(p+ω∧n)→Hq(p+ω) as n→∞. Then in (3.8) monotone (for the integrals on [0,x∨0]; recall III) and dominated (for the integrals on (−∞,0∧x]; using the assumed integrability condition and the estimate Hq(p+ω∧n)(y)≤eΦ(q+p)y for y∈(−∞,0]) convergence produce
[TABLE]
[TABLE]
Let us next write, for the purposes of the remainder of this proof only, Hq(p+ω)=:Hp and Hq(ω)=:H for short. We proceed to pass to the limit p↓0. In (3.1)-(1.1), similarly as before, by bounded (for the integral against the Lebesgue measure; recall ω is locally bounded) and monotone (for the expectation) convergence, we obtain that Hp→H as p↓0. Then in (3.9), [(ωHp)⋆W(q)](x)→[(ωH)⋆W(q)](x), as p↓0, by monotone (for the integral on (−∞,0∧x]; recall III) and bounded (for the integral on [0,x∨0]; use the facts that Hp is nondecreasing, that Hp(c) is bounded in bounded p given a fixed c∈[0,∞), and that W(q) and ω are locally bounded) convergence. Finally we consider
[TABLE]
a priori this limit must exist in [0,∞). We show that Lx does not depend on x, thus demonstrating that (3.2) is indeed satisfied for some, necessarily unique, Lq(ω)∈[0,1].
Now, since W(q) is locally bounded, since Hp is nondecreasing, and since Hp(c) is bounded in bounded p given a fixed real c, it is clear that for any choice of a∈(−∞,x],
[TABLE]
Suppose now first that ψ′(Φ(q)+)>0. Then, given any ϵ>0 we may (2.3) choose this a to be (for simplicity) ≤0 and such as to render ∣W(q)(x−y)e−Φ(q)(x−y)−1/ψ′(Φ(q)+)∣≤ϵ for all y≤a. Consequently, since (using the estimate Hp(y)≤eΦ(q+p)y for y≤0) limsupp↓0p∫−∞0Hp(y)e−Φ(q)ydy≤limp↓0Φ(q+p)−Φ(q)p=ψ′(Φ(q)+)<∞, we conclude that Lx in fact does not depend on x. For the case when ψ′(Φ(q)+)=0, i.e. the case q=Φ(q)=ψ′(0+)=0, we have that Lx=limp↓0p∫−∞aHp(y)W(x−y)dy for any a∈(−∞,x]. We argue that Q:=limsupp↓0p∫−∞aHp(y)(W(x−y)−W(a−y))dy=0 for a that are (again for simplicity) ≤0∧x, which will complete the verification that Lx does not depend on x. Indeed, since Hp(y)≤Hp(a)e−Φ(p)(a−y)≤e−Φ(p)(a−y) for y≤a≤0, we have that Q≤limp↓0p∫−a∞e−Φ(p)(y+a)(W(x+y)−W(a+y))dy=limp↓0p[eΦ(p)(x−a)(p−1−∫0x−ae−Φ(p)zW(z)dz)−p−1]=0.
The claims of ii follow at once from the above and from Lemma 11 to feature immediately.
∎
We have, regarding uniqueness of the solutions to (3.4), the following
Lemma 11**.**
Suppose (ωeΦ(q)⋅)⋆W(q) is finite-valued (which obtains if ω has a subexponential left tail). Let G:R→R be Borel measurable and locally bounded with a left tail that is Φ(q)-subexponential. Then:
(i)
limx→−∞e−Φ(q)x((ωG)⋆W(q))(x)=0.
2. (ii)
G=(Gω)⋆W(q)* implies G=0.*
3. (iii)
Let now further g:R→[0,∞) be locally bounded Borel measurable with a left tail that is Φ(q)-subexponential. Suppose G≥0 and G=g+(ωG)⋆W(q). Then G=G∞:=↑–limn→∞Gn, where the Gn are given recursively: G0:=g and Gn+1:=g+(ωGn)⋆W(q) for n∈N0.
Proof.
i. We have ∣e−Φ(q)x((ωG)⋆W(q))(x)∣≤∫−∞∞ω(y)∣G(y)∣e−Φ(q)yW(q)(x−y)e−Φ(q)(x−y)dy. Since G has a left tail that is Φ(q)-subexponential and since it is locally bounded it follows that there is a γ<∞ such that ∣G(y)∣e−Φ(q)y≤γ for all y∈(−∞,0] (say). Therefore, for x∈(−∞,0], ∣e−Φ(q)x((ωG)⋆W(q))(x)∣≤γ∫−∞∞ω(y)W(q)(x−y)e−Φ(q)(x−y)dy, which is <∞ by assumption. Now by (2.3) W(q)(x−y)e−Φ(q)(x−y) is nonincreasing to [math] as x↓−∞. Thus the conclusion follows by dominated convergence.
ii. Denote, for x∈R, ∥G∥x:=supy∈(−∞,x]∣G(y)∣e−Φ(q)y. Note this quantity is finite because G has a tail that is Φ(q)-subexponential and because it is locally bounded. Then G=(Gω)⋆W(q) implies that for all x∈R one has ∣G(x)∣e−Φ(q)x≤∥G∥x∫−∞∞ω(y)W(q)(x−y)e−Φ(q)(x−y)dy=∥G∥x(ω⋆(e−Φ(q)⋅W(q)))(x). By i(ω⋆(e−Φ(q)⋅W(q)))(x)=e−Φ(q)x((ωeΦ(q)⋅)⋆W(q))(x)→0 as x↓−∞, so there is an x0∈R such that (ω⋆(e−Φ(q)⋅W(q)))(x)≤Ix0:=(ω⋆(e−Φ(q)⋅W(q)))(x0)<1 for all x∈(−∞,x0]. At the same time, the above estimate implies ∥G∥x0≤Ix0∥G∥x0, hence ∥G∥x0=0, which forces G to vanish on (−∞,x0]. Let us now shift all the functions by x0 for (notational) convenience; to wit F:=G(x0+⋅) and θ:=ω(x0+⋅) are Borel measurable, locally bounded and F=(Fθ)⋆W(q). From this we obtain finally that F=0 by the following argument. Fix y0∈[0,∞) and let θ0 be an upper bound for θ on [0,y0]. We may choose s0∈(0,∞) such that ψ(s0)−q>θ0. Denote ∥F∥:=supy∈[0,y0]∣F(y)∣e−s0y. Then, for each y∈[0,y0], F=(Fθ)⋆W(q) and (2.2) imply ∣F(y)∣e−s0y≤∥F∥θ0∫0ye−s0(y−z)W(q)(y−z)dz≤∥F∥θ0/(ψ(s0)−q). Again this renders ∥F∥=0, and completes the proof of ii.
iii. By induction one proves that Gn≤G for all n∈N0. Moreover, passing to the limit in the recursion via monotone convergence, one finds that G∞=g+(ωG∞)⋆W(q). It follows that G−G∞ has a Φ(q)-subexponential left tail, is locally bounded, Borel measurable and satisfies G−G∞=((G−G∞)ω)⋆W(q). By ii it means that G=G∞.
∎
As is to be expected, the solution to (1.1) is associated to a family of (local) martingales. Recall the process Y from (1.2).
Proposition 12**.**
Let c∈R, γ∈(0,∞). Define the processes Z and W as follows:
[TABLE]
and
[TABLE]
Let further F=(Ft)t∈[0,∞) be any filtration relative to which X is adapted and has independent increments. Then:
(i)
The stopped process Zτc+ is a bounded càdlàg martingale in the filtration F under Px for each x∈R; for real x≤c the Px-terminal value of this martingale is Hq(ω)(c)exp{−∫0τc+ω(Xs)ds−qτc+}\mathbbm1{τc+<∞}.
2. (ii)
Assume ω is strictly positive and eq is independent of F∞ (under Px for each x∈R). Then the stopped process WTc+ is a càdlàg bounded martingale in the filtration G=(Gs)s∈[0,∞):=(Fρs∨σ({{ρu<eq}:u∈[0,s]}))s∈[0,∞) under Px for each x∈R.
Remark 13*.*
As a check, since WTc+ has a constant expectation, we recover (1.3) in the limit as time goes to infinity.
Proof.
We may assume x≤c.
i. Let t∈[0,∞). Then in Markov process theory parlance (for notational simplicity only; ultimately no shift operators are of course needed here) τc+∧t+τc+∘θτc+∧t=τc+ and Px-a.s. Zt∧τc+=Hq(ω)(c)exp(−∫0t∧τc+ω(Xu)du−q(t∧τc+))PXt∧τc+[exp{−∫0τc+ω(Xu)du−qτc+};τc+<∞]=Hq(ω)(c)Px[(exp{−∫0τc+ω(Xu)du−qτc+}\mathbbm1{τc+<∞})∘θτc+∧texp{−∫0t∧τc+ω(Xu)du−q(t∧τc+)}∣Ft∧τc+]=Hq(ω)(c)Px[exp{−∫0τc+ω(Xu)du−qτc+}\mathbbm1{τc+<∞}∣Ft∧τc+]=Hq(ω)(c)Px[exp{−∫0τc+ω(Xu)du−qτc+}\mathbbm1{τc+<∞}∣Ft], which establishes the first claim.
ii. For all real 0≤s≤t, A∈Fρs, applying the optional sampling theorem to the process Zτc+ at the times ρs and ρt, we obtain
[TABLE]
[TABLE]
i.e., because ρt∧τc+=ρt∧ρTc+=ρt∧Tc+ on {ρt∧τc+<eq}={t∧Tc+<ζ}, since ρ is the inverse of ∫0⋅ω(Xu)du, and by the independence of eq from F∞,
[TABLE]
This implies that (e−sHq(ω)(Ys)\mathbbm1{s<ζ})s∈[0,∞) stopped at Tc is a martingale in the filtration G under Px, because this process is constant on [ζ,∞), and since for s∈[0,∞), {s<ζ}={ρs<eq} with the equality of the trace σ-fields Gs∣{ρs<eq}=Fρs∣{ρs<eq} holding true. Replacing ω with γω shows the same is true of the process (e−γsHq(γω)(Ys)\mathbbm1{s<ζ})s∈[0,∞) stopped at Tc+.
∎
Apart from the solutions presented in Examples 5, 6, 8 and 9, it seems difficult to come up with “nice” ω for which Hq(ω) is given explicitly (in terms of ψ and Φ, say), at least for a general W(q). However, based on Example 6, we can “reverse-engineer” a class of ω for which Hq(ω) is explicit, in the precise sense of
Proposition 14**.**
Let ν be a probability measure on the Borel sets of (0,∞) whose support is compactly contained in (0,∞). Denote, for α∈(0,∞), Hα:=Hq(eα⋅) and Lα:=Lq(eα⋅). Then H=Hq(ω) and L=Lq(ω), where L:=∫Lαν(dα) and, for x∈R, H(x):=∫Hα(x)ν(dα) and ω(x):=∫Hα(x)ν(dα)∫Hα(x)eαxν(dα).
Proof.
The fact that ν has a bounded support ensures that H is locally bounded. We know Hα=LαeΦ(q)⋅+(eα⋅Hα)⋆W(q) for each α∈(0,∞). Integrating both sides against ν(dα) we obtain via Tonelli’s theorem (relevant measurabilities follow from the explicit form of the Hα given in Example 6) H=LeΦ(q)⋅+(Hω)⋆W(q). At the same time, for x∈(−∞,0], e−Φ(q)xH(x)=∫Hα(x)e−Φ(q)xν(dα)≤1 so H:R→(0,∞) has a left tail that is Φ(q)-subexponential. Next, because the support of ν is bounded from below away from zero, ω has a subexponential left tail. By Lemma 11 we obtain H=Lq(ω)LHq(ω). But we also have H(1)=1=Hq(ω)(1), hence L=Lq(ω), and the proof is complete.
∎
Another fairly general class of ω that can be handled with some success is considered in
Remark 15*.*
Let P be a real polynomial, α∈(0,∞) and c∈R. Suppose ω(x)=P(x)eαx for all x∈(−∞,c]. Then the recursion of Theorem 2ii can, on (−∞,c], be successively computed in essentially closed form: one obtains algebraic expressions involving only ψ and its higher-order derivatives. This is because, together with the Laplace transform of W(q) (2.2) that is given in terms of ψ, one obtains, by successive differentiation, also expressions for its higher order derivatives. In a similar vein, if c<0 and ω(x)=P(1/x)eαx for x∈(−∞,c], then one gets iterated integrals involving ψ (cf. Example 9).
Finally, when given a concrete W(q), it may of course very well happen that for a specific form of ω, the convolution equation of Theorem 2ii admits an explicit solution (even as it fails to do so for a general W(q)). A flavor of this is given in the next section.
4. Application to a model for the price of a financial asset
Assume ω>0. We consider the process S defined by
[TABLE]
as a model for the price of a (speculative) financial asset (here Y is the process from (1.2)). When ω=1, then ζ=eq, X=Y on [0,eq), and S is nothing but the classical exponential Lévy model for the price of a risky asset (defaulted at ζ), see [11] for a recent review. The idea with allowing a more general ω is that the asset price may “move faster or slower along its trajectory”, depending on the price level, destroying the stationary independent increments property of the log-returns, but preserving their Markovian character.
Using time changed Lévy processes to model financial assets is of course not new, see e.g. [2, 6]. We set Qz:=Plogz, z∈(0,∞), for convenience.
Suppose then in this setting that we are interested in the simple problem of the determination of the optimal level b at which to sell the asset, having bought it at the level z∈(0,∞), under an inflation/impatience rate γ∈[0,∞). In other words, if we let Rb+:=inf{s∈(0,∞):Ss>b} denote the first hitting time of the set (b,∞) by the process S, then we would like a solution to the problem
[TABLE]
(More generally we may simply be interested in A(b) itself, if we are predetermined to sell at the level b∈[z,∞).) But, for b∈[z,∞), since SRb+=b on {Rb+<∞},
[TABLE]
Hence (4.1) is intimately related to the determination of the quantity (1.1).
Now if ω=1, then, of course, because of the martingale property of (exp{Xt−ψ(1)t})t∈[0,∞) and the optional sampling theorem, A(b) is monotone in b∈[z,∞), and the problem is trivial. However, for a general ω this is no longer the case, as we will see on an example shortly.
Let indeed α∈(0,∞) and ω=eα⋅∧1: as a possible rationale for such a choice, one may imagine that the asset moves faster along its trajectory at smaller price levels, reflecting that the investors are then more jittery, increasing the velocity of the trades. In this case we can be quite explicit about the nature of Hq(γω)=:H, as follows. Denote L:=Lq(γω), and by P the Patie scale function (3.6) of Example 6, so that L=(∑k=0∞akγk)−1 and
[TABLE]
where we have set ak:=(∏l=1k(ψ(Φ(q)+lα)−q))−1 for k∈N0. Then H=P on (−∞,0], while for x∈[0,∞),
[TABLE]
where
[TABLE]
As in the proof of Lemma 11 one sees that, on [0,∞), H=↑–limn→∞Hn where H0:=h and then recursively Hn+1=h+γHn⋆W(q) for n∈N0, the latter convolution being now on [0,∞). Taking Laplace transforms on [0,∞) in (4.2) (denoting them by a hat) and using (2.2), it is also true that H^(s)=h^(s)+γH^(s)/(ψ(s)−q) and hence
[TABLE]
(using Theorem 2III and the known solution for ω=1 it is easily checked that H^(s)<∞ for s∈(Φ(q+γ),∞)).
Now if q+γ<ψ(1), then a comparison argument (with ω=1) shows that A(b)→∞ as b→∞. However, in general, it does not seem obvious how to determine an optimal b analytically, nor is it our intent to pursue this further here; we content ourselves by demonstrating how A(b) may fail to be monotone in b. This transpires already in the (presumably simplest) case when ψ(s)=s2, s∈[0,∞), corresponding to X being a multiple (by the factor 2) of Brownian motion, and q=0, α=z=1. Under the latter specifications, Φ(0)=0 and ψ(1)=1, while W(x)=x and (via (4.3)) h(x)=1+bγx, x∈[0,∞), where bγ:=γ∑k=0∞k!2(k+1)γk/∑k=0∞k!2γk. Inverting the Laplace transform (4.4) for H we obtain
The reference list from the paper itself. Each links out to its DOI / PubMed record.
1[1] J. Bertoin. Lévy Processes . Cambridge Tracts in Mathematics. Cambridge University Press, Cambridge, 1996.
2[2] P. Carr and L. Wu. Time-changed Lévy processes and option pricing. Journal of Financial Economics , 71(1):113 – 141, 2004.
3[3] R. A. Doney. Fluctuation Theory for Lévy Processes: Ecole d’Eté de Probabilités de Saint-Flour XXXV - 2005 .
4[4] Leif Döring and A. E. Kyprianou. Perpetual integrals for Lévy processes. Journal of Theoretical Probability , 29(3):1192–1198, 2016.
5[5] X. Duhalde, C. Foucart, and C. Ma. On the hitting times of continuous-state branching processes with immigration. Stochastic Processes and their Applications , 124(12):4182 – 4201, 2014.
6[6] S. Klingler, Y. S. Kim, S. T. Rachev, and F. J. Fabozzi. Option pricing with time-changed Lévy processes. Applied Financial Economics , 23(15):1231–1238, 2013.
7[7] A. Kuznetsov, A. E. Kyprianou, and V. Rivero. The theory of scale functions for spectrally negative Lévy processes. In Lévy Matters II: Recent Progress in Theory and Applications: Fractional Lévy Fields, and Scale Functions , pages 97–186. Springer Berlin Heidelberg, Berlin, Heidelberg, 2013.
8[8] A. E. Kyprianou. Fluctuations of Lévy Processes with Applications: Introductory Lectures . Springer-Verlag, Berlin Heidelberg, 2014.

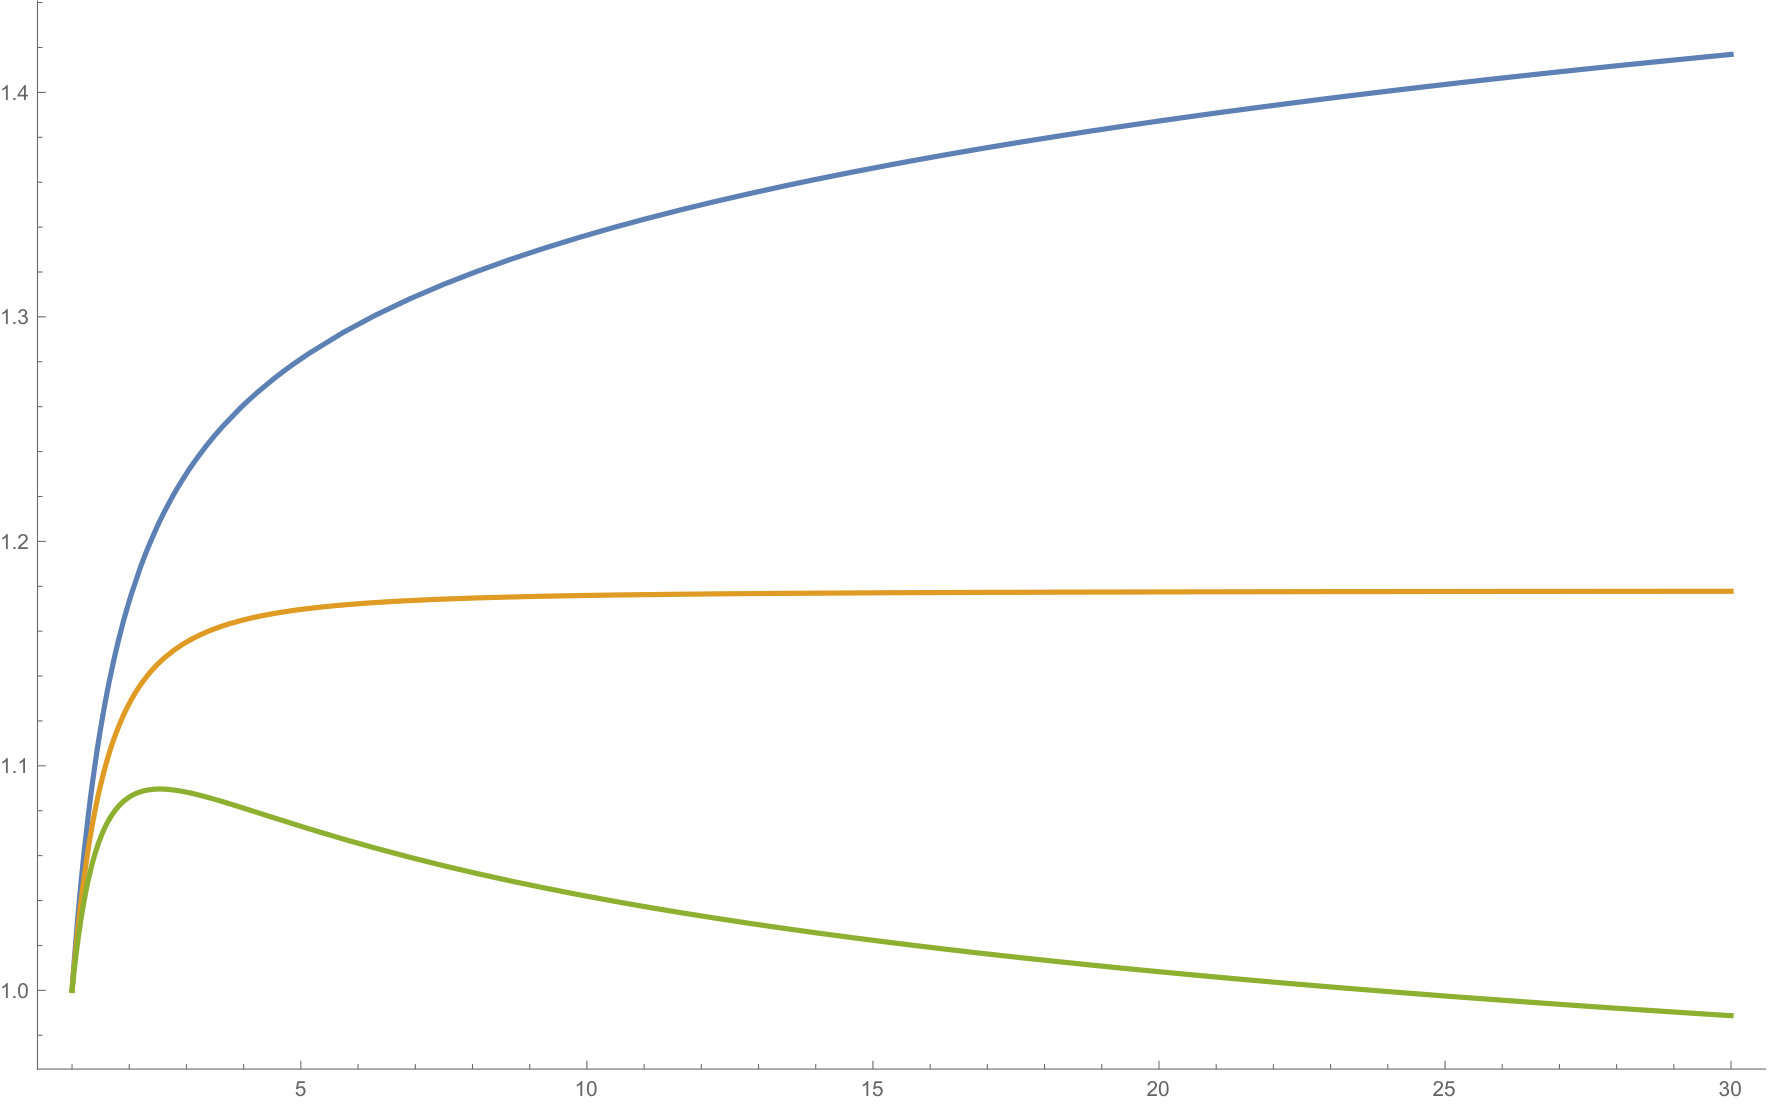 Figure 1