Approximation of the distribution of a stationary Markov process with application to option pricing
Gilles Pag\`es (PMA, LSProba), Fabien Panloup (PMA)

TL;DR
This paper develops a method to approximate the distribution of stationary Markov processes, with applications to option pricing in stochastic volatility models, through empirical measures and convergence analysis.
Contribution
It introduces a new approach to approximate stationary Markov process distributions and applies it to option pricing, demonstrating efficiency in stochastic volatility models.
Findings
Convergence results for empirical measures approximating Markov processes.
Application to Brownian diffusions and Lévy-driven SDEs under stability conditions.
Efficient numerical method for option pricing in complex models.
Abstract
We build a sequence of empirical measures on the space D(R_+,R^d) of R^d-valued c\`adl\`ag functions on R_+ in order to approximate the law of a stationary R^d-valued Markov and Feller process (X_t). We obtain some general results of convergence of this sequence. Then, we apply them to Brownian diffusions and solutions to L\'evy driven SDE's under some Lyapunov-type stability assumptions. As a numerical application of this work, we show that this procedure gives an efficient way of option pricing in stochastic volatility models.
Click any figure to enlarge with its caption.
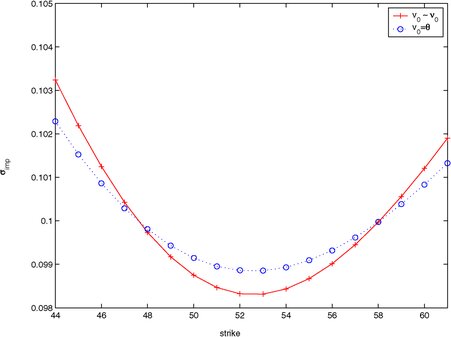 Figure 1
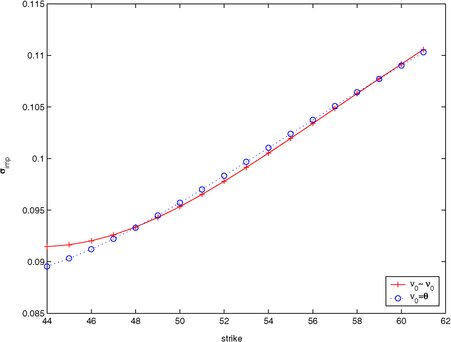 Figure 2
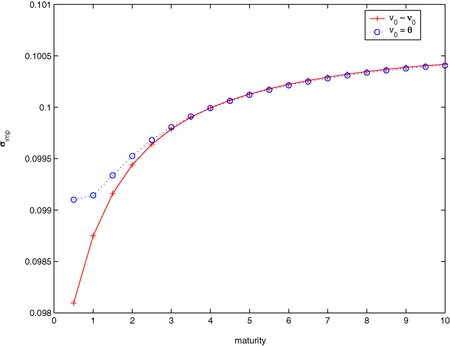 Figure 3
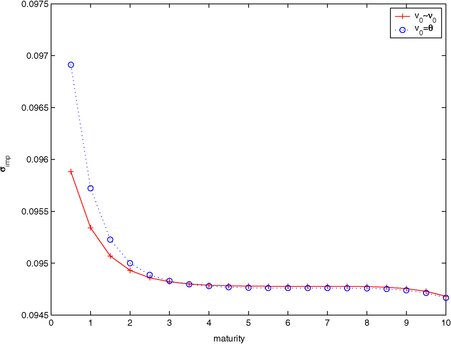 Figure 4
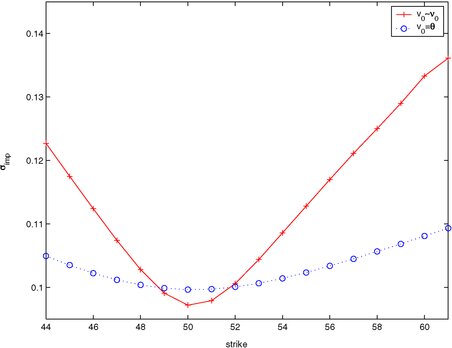 Figure 5
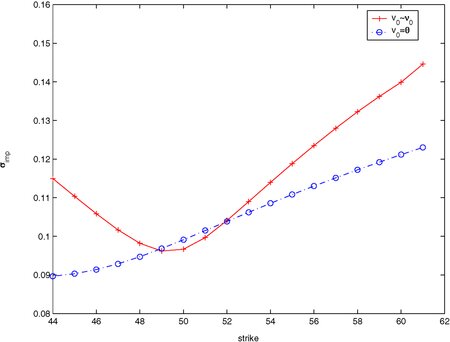 Figure 6
Peer Reviews
No public reviews on file for this paper yet. If you reviewed it on a platform where reviews are public (OpenReview, ICLR, NeurIPS, ICML), you can paste yours below so the community can read it here.
Videos
No videos yet. Explain this paper in a talk, walkthrough, or lecture? Add one.
Taxonomy
TopicsStochastic processes and financial applications · stochastic dynamics and bifurcation · Financial Risk and Volatility Modeling